
In a disappointing turn for the cryptocurrency industry, the years-in-the-making Crypto
Clarity Act failed to get a majority of votes in the U.S. Senate, leaving the industry once
again without a federally mandated set of rules.
The industry spent years and hundreds of millions of dollars trying to bring Congress to an
approval of some level of market structure legislation, and while a vote on the Senate floor
is the furthest the effort has progressed, it is still a major blow to the army of lobbyists,
advocacy groups, political action committees and high-profile crypto executives who all
fostered the new law.
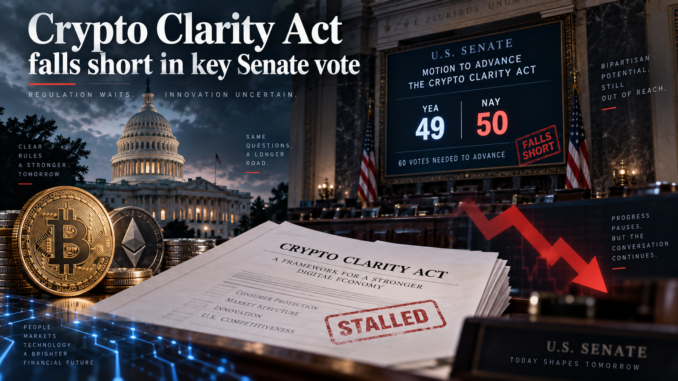
A 49-50 vote on Tuesday was far short of the 60 required Senate votes to advance the bill.
The fact that it failed to win even a majority of votes leaves the process in a tough position.
Barring some sort of long-shot effort aimed at the final weeks of this Congressional session
beyond the mid-term elections, industry leaders will likely head back to the drawing board.
The bipartisan effort contained more than 600 pages of legislative compromise, however,
the final sections of the bill, which included ethics provisions meant to curtail senior
government officials from maintaining crypto business ties, turned out to be stumbling
blocks. And the closer the vote came to the mid-terms, the more likely it was that political
pressure would get in the way of bipartisan cooperation.
The core idea of the Clarity Act is to clearly define how the government would approach
different types of cryptocurrencies and lay out specific roles for regulatory agencies,
including new authority for the Commodity Futures Trading Commission to be a watchdog
for crypto spot markets.
“Do not let this day be the day we handed our future to someone else because we were too
afraid to finish what we started,” said Senate Republican Cynthia Lummis, who failed to
convince enough of her colleagues to join her. “Let’s vote yes. Let’s not only join the 21st
Century economy, let’s define it.”
The industry will now likely lean on U.S. market regulators to impose rules on the sector.
The Securities and Exchanges Commission and the CFTC have begun moving forward on
initiatives the industry hopes will provide stability and certainty to lure more investors and
businesses off the sidelines and into the crypto arena.
The SEC recently proposed the Regulation Crypto Assets plan which allow crypto projects
to raise money and establish themselves without immediately drawing difficult regulatory
requirements. And the agency is ready to approve a narrow version of securities
tokenization that could eventually remake how security transactions are executed in the
U.S.
However, it’s worth noting that crypto rules and exemptions from registration demands
won’t hold up with laws to underpin them.
The industry’s PACs will have to decide what to do with the politicians who voted against
the measure in these final weeks before the mid-terms, including current majority
members who will have authority over future crypto legislative efforts. Industry PACs will
likely continue to support more crypto-friendly members of Congress in the hope that an
inevitable tipping point will be reached in support of future legislation.
Digital asset advocates did score a legislative win in 2025 when the Guiding and
Establishing National Innovation for U.S. Stablecoins (GENIUS) Act earned bipartisan
approval and became law.
Industry insiders saw that as a major win given the crypto failures and high-profile scandals
of 2022. With a new Congress to be seated in January, and a potential shift in the balance
of power, insiders expect the next Congress to spend some time investigating the Trump
administrations involvement with crypto businesses and some of their leaders, before
focusing on market structure legislation.

Be the first to comment