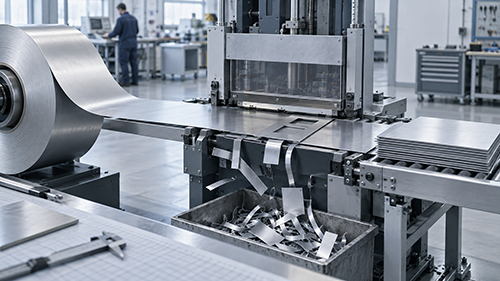

A supplier’s invoice shows how much material entered a business, but it does not show how much eventually became usable or sellable. Normal material loss and inconsistent output can increase a finished product’s cost without showing up as separate expenses.
Material yield fills in that missing part of the picture. It measures the percentage of purchased material that becomes usable output. Understanding how material yield changes a company’s real unit cost can help owners price their work more accurately and compare purchasing options on equal terms.
Look Beyond the Purchase Price
Many cost calculations begin with the amount purchased. If a company pays $500 for 100 linear feet of material, the recorded price is $5 per foot. That figure is correct when the shipment arrives, but it may not reflect what the material actually costs once production begins.
The business may have to remove damaged sections or make cuts that leave unusable remnants. Some material may also fail to meet the finished product’s quality requirements. If only 82 feet can be used, dividing the purchase cost by all 100 feet understates what the finished work actually consumes.
This distinction matters whenever a company turns purchased inputs into something customers can buy. A printer pays for sheets lost during setup as well as those included in the final order. A flooring installer may purchase material that cannot be incorporated into the completed job. In both cases, the invoice price and usable-unit cost tell different stories.
Calculate Yield Before Calculating Unit Cost
Owners do not need complicated accounting software to run a basic yield calculation. They need one consistent unit of measurement and reliable records of what entered and left the process.
Material yield = usable material ÷ purchased material × 100
In the earlier example, 82 usable feet divided by 100 purchased feet produces an 82 percent yield. That percentage becomes more useful when it is carried into the cost calculation:
Real cost per usable unit = total material cost ÷ usable output
The $500 purchase divided by 82 usable feet produces an effective cost of approximately $6.10 per foot. The supplier did not raise the price, but each usable foot costs the business $1.10 more than the purchase record suggests.
A business can measure yield by weight or by individual piece. It simply needs to use the same unit on both sides of the calculation.
Separate Normal Loss From Unexpected Variation
A lower yield does not automatically mean something is wrong. Some processes require material removal to meet a customer’s dimensions or quality standards. A butcher must trim certain cuts, and a cabinetmaker cannot use every inch of a board. Treating all loss as preventable would create an unrealistic target.
The more useful question is whether the result falls within the company’s normal range. If several comparable runs consistently produce yields between 80 and 84 percent, the business has a reasonable baseline for pricing and purchasing. A later run that falls to 68 percent deserves a closer look.
Comparisons must involve similar materials and finished products. A complex custom order may naturally produce more offcuts than a standard item. Separating those jobs prevents owners from mistaking a product requirement for a performance problem.
Find Where Usable Output Changes
When yield moves outside its normal range, start with the material. A lower-priced shipment may contain more defects or arrive in less consistent dimensions. Paying less upfront provides little advantage if the company must purchase additional material to complete the same number of orders.
Next, look at what happens during production. Equipment that cuts unevenly or loses accuracy can reduce output gradually, making the added cost easy to miss. A process change may have a similar effect even when employees follow the instructions they received.
In a commercial kitchen, tracking usable portions during food prep can show whether trimming, inconsistent preparation, or portioning is raising the real cost of each serving. The same principle applies when another business cuts fabric or prepares installation materials.
The instructions may be part of the problem, too. Two employees may produce different results because one received an updated specification and the other did not. Before blaming an employee, managers should confirm that the material and equipment settings were comparable. They should also verify the expected output.
Compare Several Runs Before Drawing Conclusions
One unusual result can reveal a problem, but it does not always establish a pattern. A damaged shipment or unusually complex order may explain a temporary drop. Owners can make stronger decisions by tracking several comparable runs and noting the circumstances around each one.
The record does not need to be elaborate. It can show the material purchased and usable output. The business can also note the job type and reason for any known loss. Over time, those entries can show whether lower yield follows a particular supplier or process.
This approach also keeps the review constructive. Employees are more likely to report damaged material and unclear instructions when the measurement is used to improve the process rather than assign automatic blame. Better reporting gives management a more accurate explanation for the cost difference.
Apply Yield Data To Everyday Decisions
Once owners see how material yield affects real unit costs, the number can improve several routine decisions.
Set Prices From Usable Output
Pricing based on an ideal yield can leave the business absorbing costs whenever actual results fall short. A realistic baseline gives owners a stronger foundation for quotes and product margins.
Compare Suppliers by Usable Cost
The lowest price per purchased unit may not represent the best value. A slightly more expensive material can cost less per finished unit if its quality produces a consistently higher yield.
Evaluate Process Changes With Evidence
A proposed change should produce a measurable result. Comparing yield before and after implementation helps owners determine whether it improved usable output enough to justify its cost.
Yield data should support judgment rather than replace it. Quality standards and production capacity still affect business decisions. The calculation simply makes one commonly hidden cost easier to see.
Start With One High-Cost Material
A company does not need to measure every input at once. Starting with one frequently purchased material keeps the process manageable and makes errors easier to spot.
- Record the quantity purchased and its total cost.
- Measure the amount that becomes usable output.
- Calculate the yield percentage.
- Compare several similar jobs or production runs.
- Recalculate the cost per usable unit.
Once the measurement is dependable, the company can apply the same process to another important material. A focused rollout is more useful than collecting a large amount of inconsistent data.
Protect Margins With Better Cost Data
Purchase records remain essential, but they cannot show what happens after materials enter the business. Yield connects those records with the amount that can actually support a customer order.
When owners calculate costs from usable output, they gain a clearer basis for pricing and supplier comparisons. They can also investigate unusual losses without assuming that every offcut or rejected piece reflects carelessness. One straightforward measurement can reveal whether a material is delivering the value its invoice appears to promise.
Be the first to comment